Qualifying for an Assumable Mortgage
How to qualify for an assumable mortgage: the credit, income and debt requirements lenders check before you can take over a loan.
Key takeaways
How to Qualify for an Assumable Mortgage
Qualifying for an assumable mortgage means meeting the requirements set by the lender on the existing mortgage you wish to take over. While assumable mortgages allow buyers to assume the seller's loan with its original terms and interest rate, lenders still need to ensure that the buyer is financially capable of repaying the loan. This means you will go through a qualification process similar to applying for a new mortgage.
Key Qualification Criteria for Assumable Mortgages
When applying to assume a mortgage, your lender will evaluate several factors to determine your eligibility. Below are the main criteria:
1. Credit Score Requirements
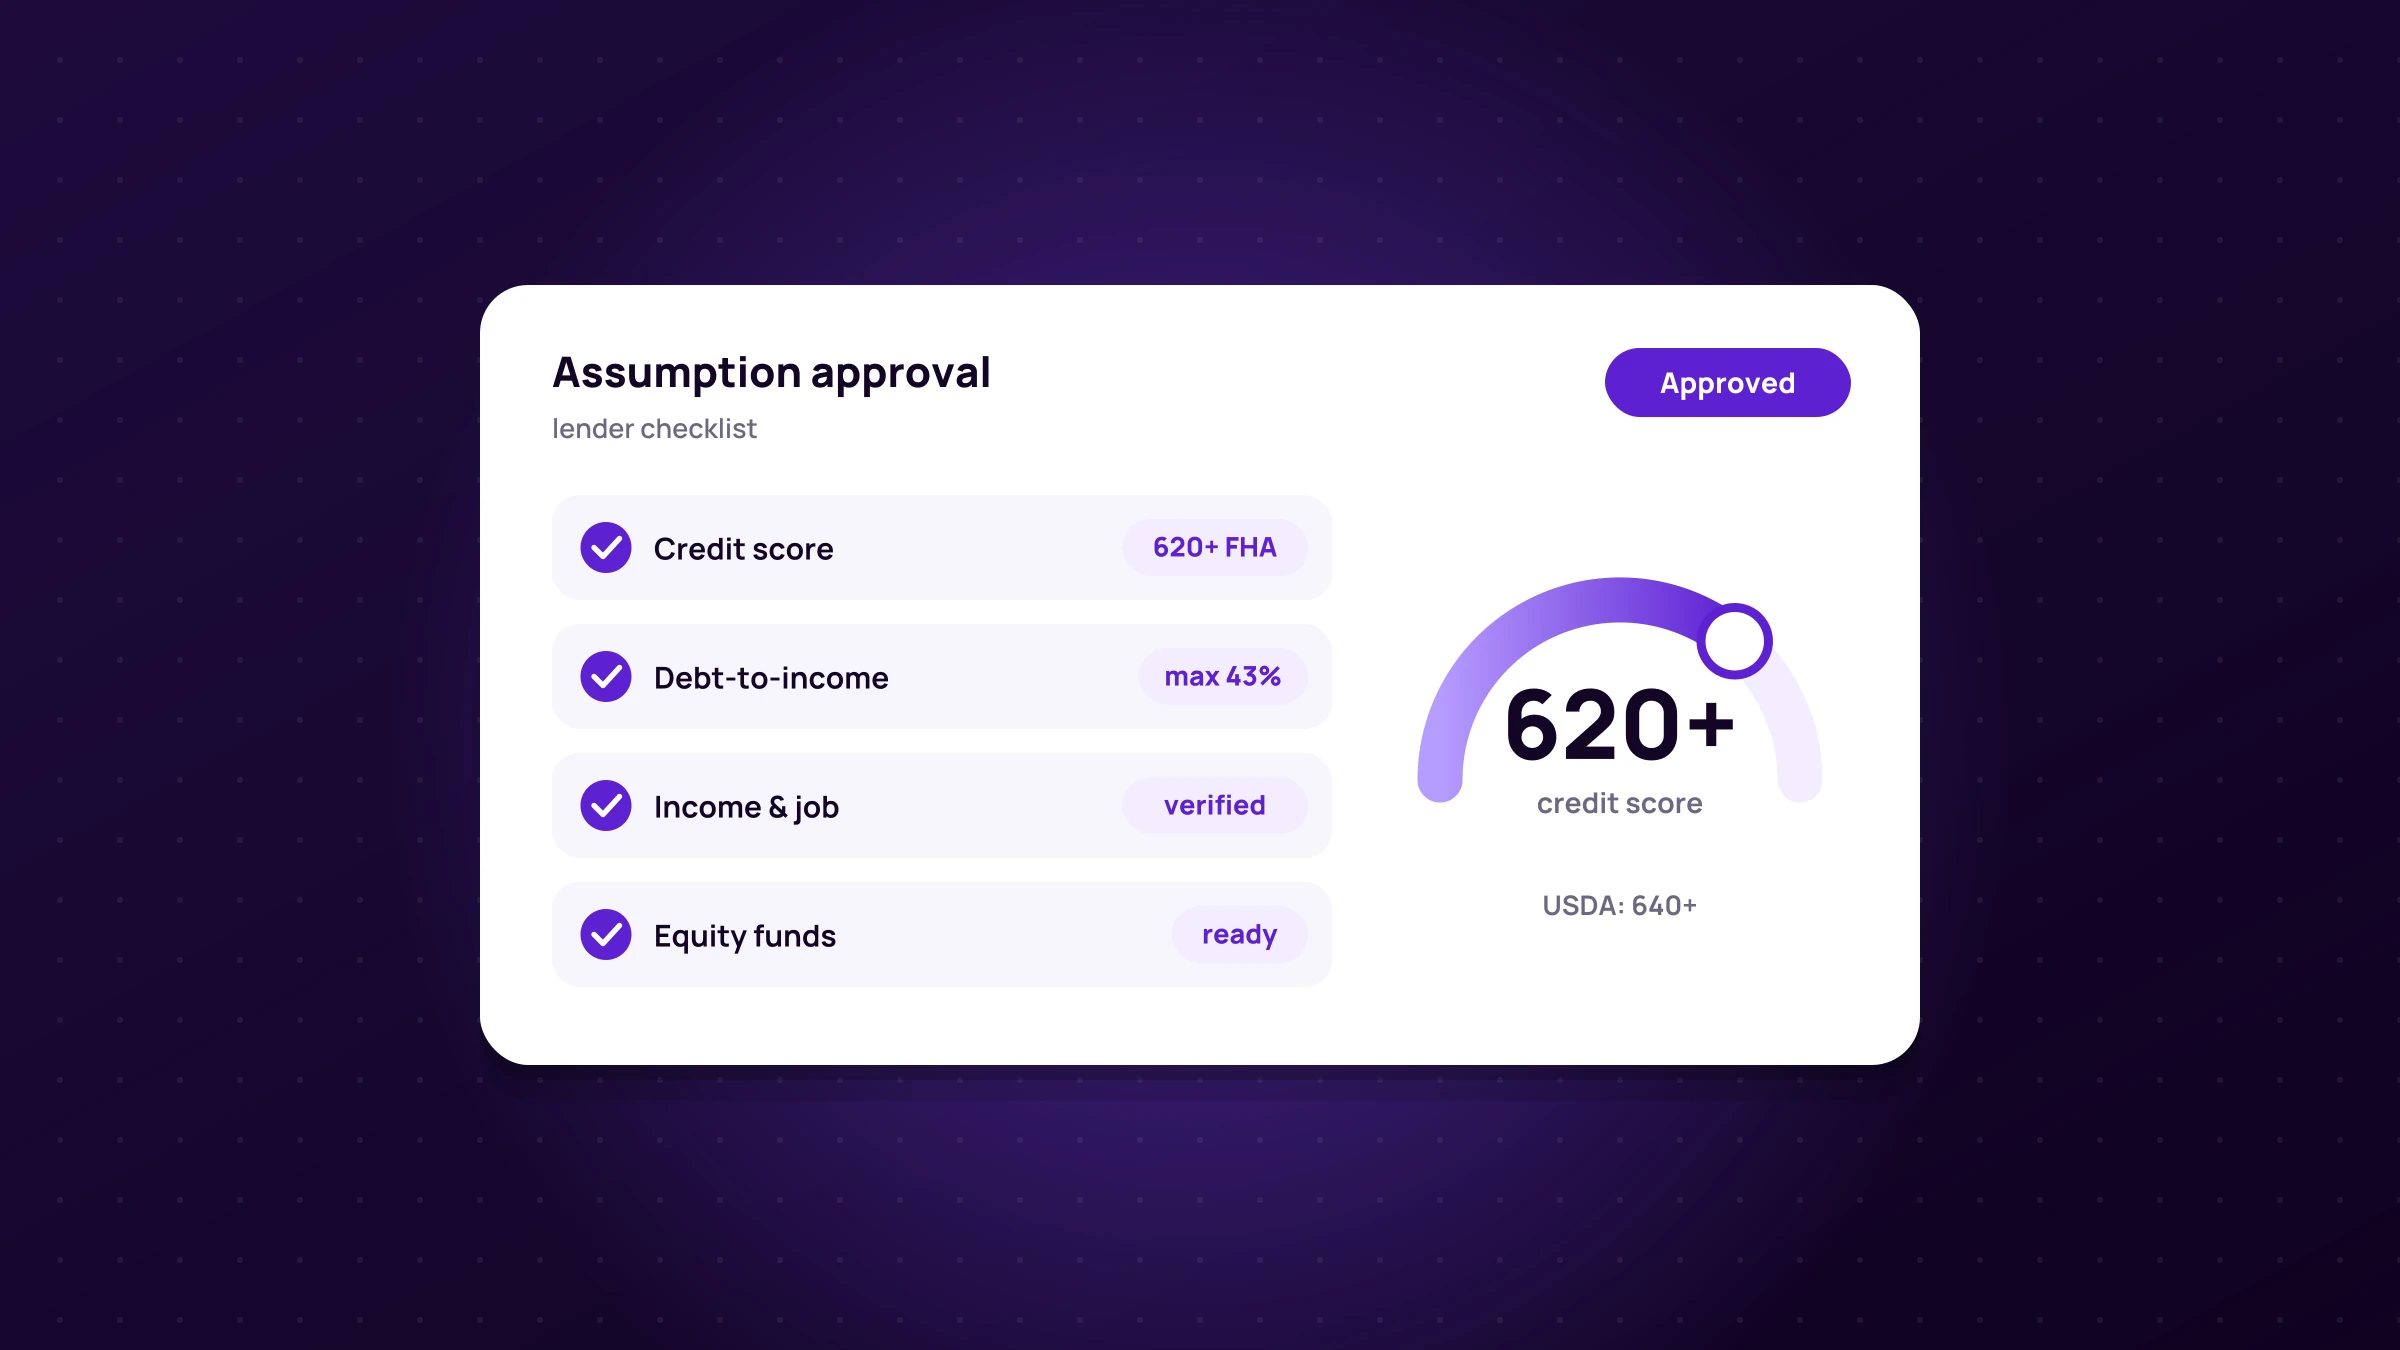
- FHA Loans: Most lenders look for a minimum credit score of around 620. Some may accept slightly lower scores with extra conditions.
- VA Loans: Similar creditworthiness is required, but the VA does not set a strict minimum score.
- USDA Loans: A minimum credit score of 640 is typically needed.
Your credit history will also be checked to evaluate your reliability in repaying debts.
2. Income & Employment Verification
You must demonstrate stable and sufficient income to cover the mortgage payments. Lenders will verify your employment status and request income documentation such as pay stubs and tax returns. These documents are used to calculate your debt-to-income (DTI) ratio. For FHA loans, the DTI ratio must generally not exceed 43%, though exceptions up to 50% may be possible.
3. Paying the Equity Difference
Assumable mortgages require you to pay the seller for the home equity, which is the difference between the home's current value and the remaining mortgage balance. You must have funds available for this upfront cost, either in cash or through secondary financing.
Lender Approval Process
Even if you're assuming an existing loan, the lender's approval is required. The lender will review your financial qualifications to ensure you can handle the mortgage payments. This approval protects both you and the lender by confirming that the loan remains secure.
- FHA Loans: For loans originated after 1989, lender approval is mandatory.
- VA Loans: For loans originated after 1988, lender approval is mandatory.
- Loans originated before these dates may be freely assumable without lender approval.
Other Important Considerations
- The property typically must meet eligibility criteria, such as being the seller's primary residence in many cases.
- You may be responsible for paying assumption fees, which can vary by loan type.
- VA loan assumptions may also require paying a funding fee.
Ready to Begin Your Mortgage Assumption Journey?
For more information and personalized guidance, use our app or become an Assumable.io client to navigate the mortgage assumption process with confidence.