Assuming VA Loans: Important Details
You don't need military service to assume a VA loan. Who can assume one, how the process works and what it means for the seller's entitlement.
Key takeaways
Can Anyone Assume a VA Loan? Understanding VA Loan Assumption
Who Can Assume a VA Loan?
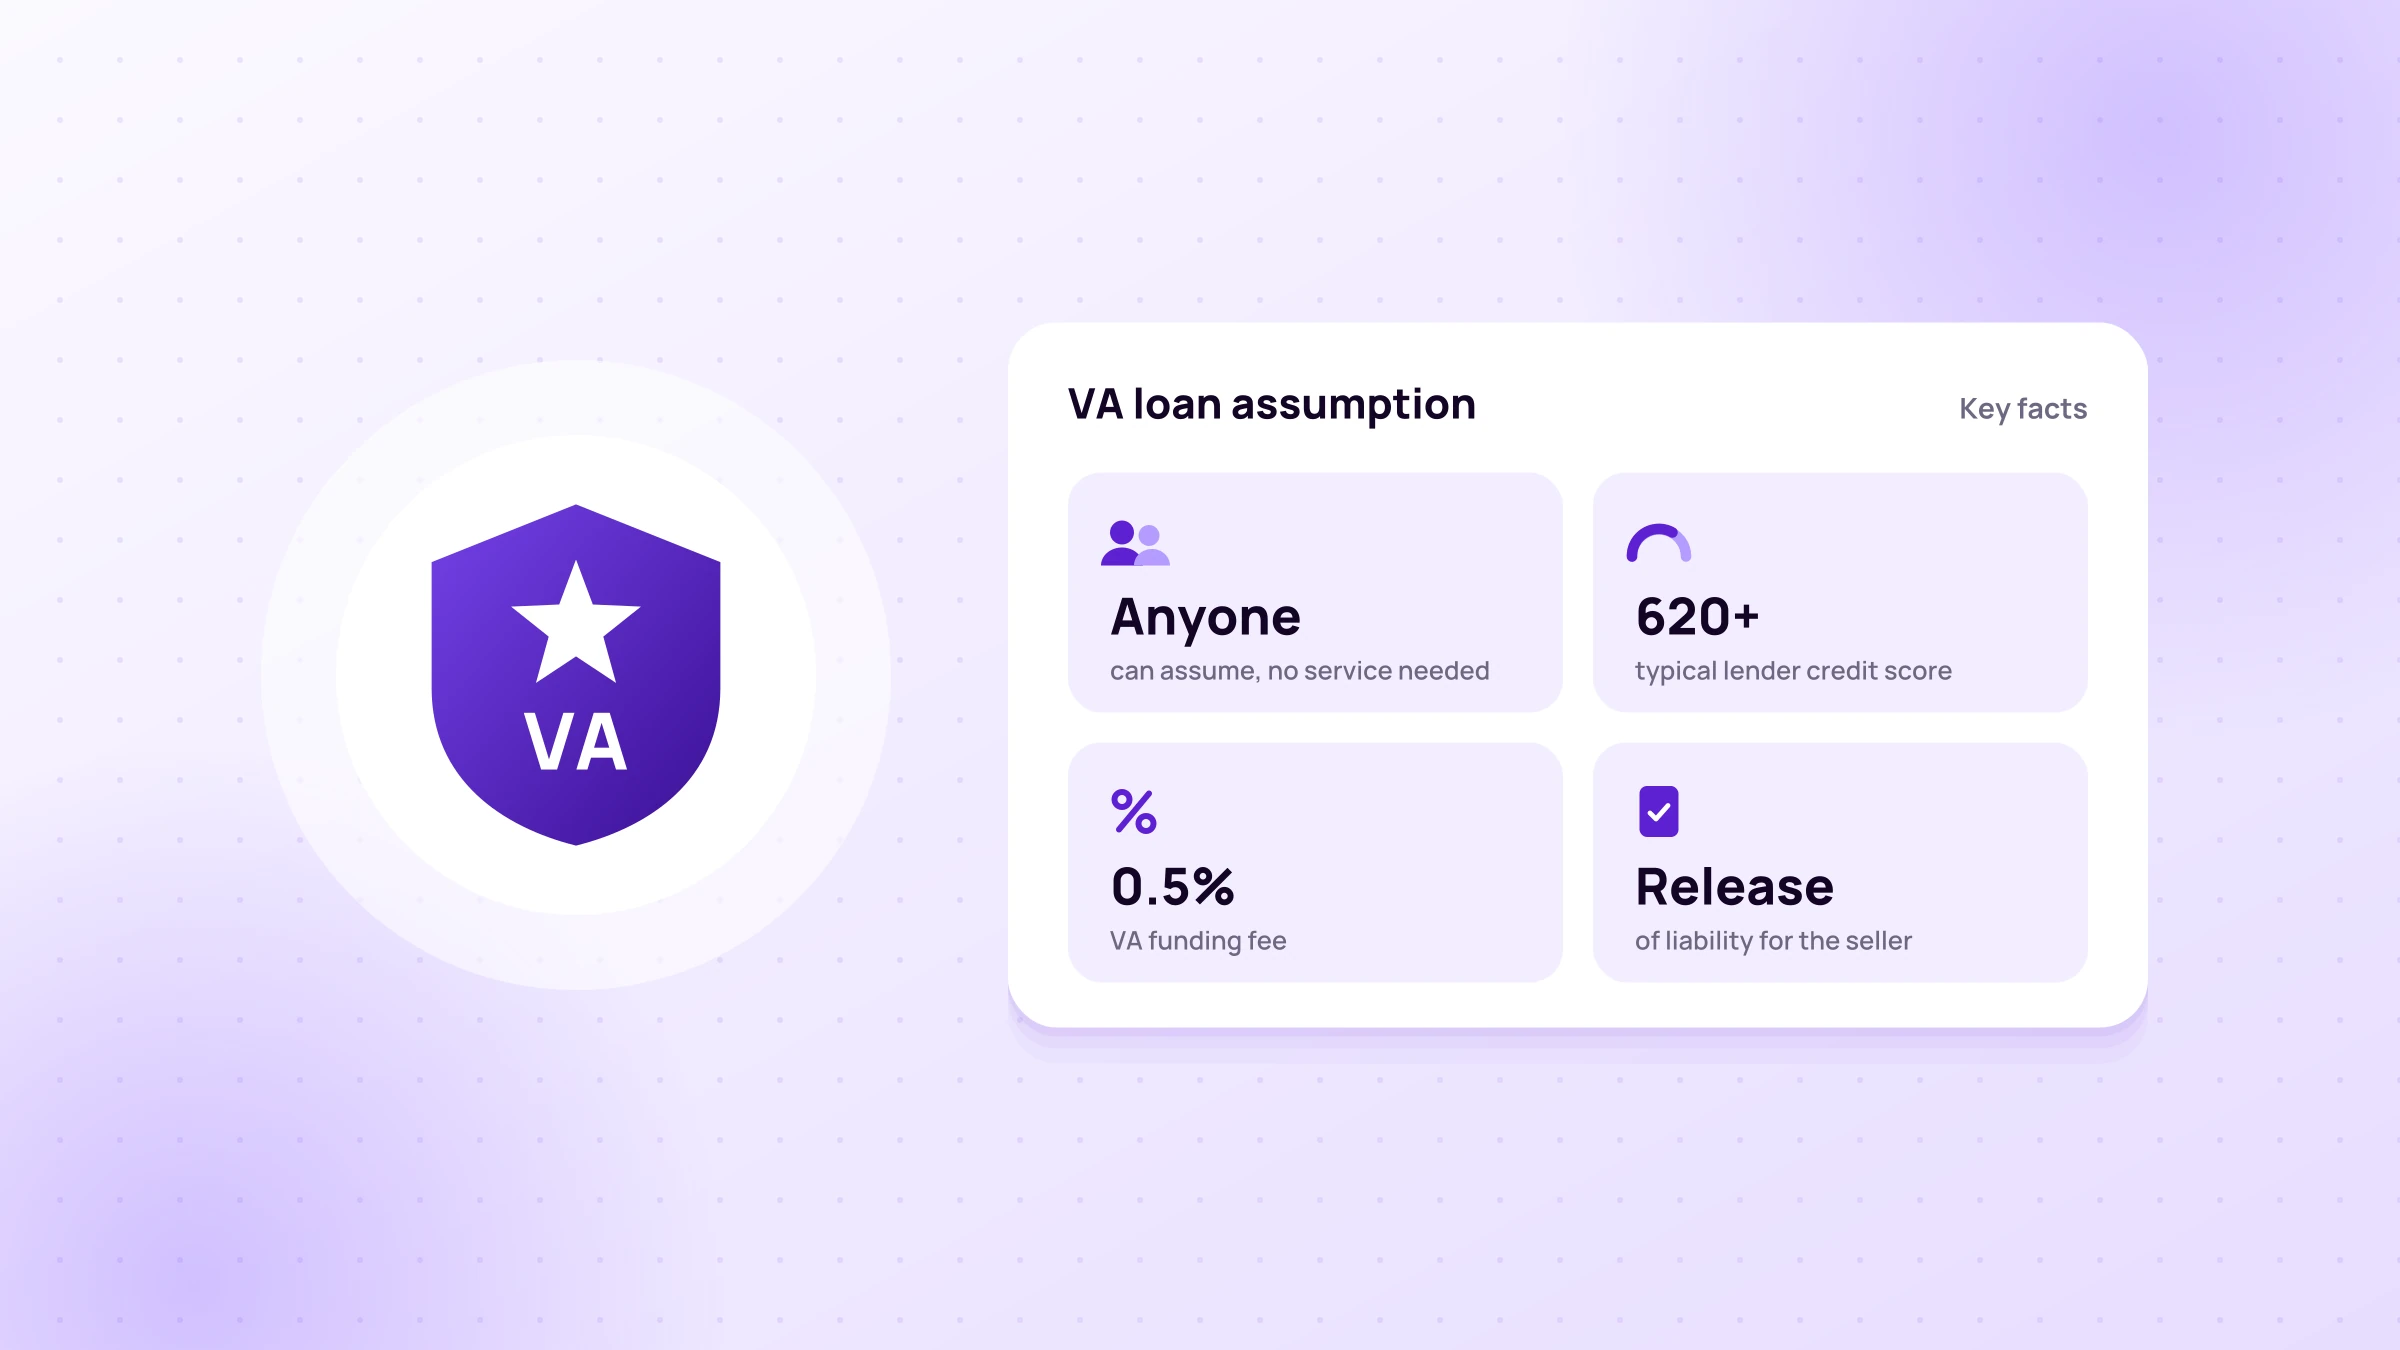
Contrary to popular belief, you don't need to have served in the military to assume a VA loan. Anyone can assume a VA loan; military service isn't a requirement (since you're not originating this loan, simply assuming it). This unique feature makes VA loans very attractive in today's housing market, especially when current mortgage rates are higher than the original loan's rate. Let's explain this in more detail below.
How VA Loan Assumption Works
When a VA loan is assumable, the buyer takes over the seller's existing mortgage. This assumption includes the current low interest rate and the remaining loan balance. As a result, buyers can experience significant monthly savings compared to getting a brand-new loan at today's higher rates.
However, buyers must still meet the credit and income requirements set by the lender to qualify for a mortgage assumption.
Important Considerations: VA Entitlement & Eligibility
While anyone can assume a VA loan, the VA benefits and entitlement stay with the home. In other words, the seller's VA loan entitlement remains tied to the property until the loan is paid off. This is a key consideration for veterans because their entitlement can only be restored when the loan is fully repaid or refinanced.
This often leads to a community of veterans helping other veterans by assuming these loans. However, non-veterans can also qualify if they meet the lender's criteria.
Mortgage Assumption Requirements
- Lender Approval: Mortgage assumption only works when the lender approves it.
- Credit & Income: Buyers must provide financial documentation to show the ability to repay the loan.
- Credit Score: The VA itself does not set a minimum credit score, but lenders typically require a score of 620 or higher.
- Income Stability & Debt-to-Income Ratio: Lenders assess income stability and DTI ratio.
- VA Funding Fee: A 0.5% VA funding fee usually applies to the assumption (lower than the fee for first-time VA loans).
Seller Responsibilities: Get a Release of Liability
As a seller, you must obtain a "release of liability" from the lender to avoid future responsibilities for the loan after the assumption. Without this release, the seller might remain liable if the buyer defaults.
Summary: Key Points on VA Loan Assumption
- Both veterans and non-veterans can assume a VA loan if they meet lender requirements.
- The VA benefit stays with the home and affects entitlement restoration for the veteran.
- Lender approval and financial qualification are necessary.
- A 0.5% funding fee typically applies to the assumption.
Find Assumable Mortgages
Ready to explore your options? Use the Assumable web app, where we showcase many assumable mortgage listings available.