Low-Rate Assumable Loans: A Short Explanation
What a low-rate assumable loan is, which mortgages are assumable, and how taking over a seller's rate lowers your monthly payment.
Key takeaways
What Is a Low-Rate Assumable Loan?
A low-rate assumable loan lets you take over someone else's existing home loan, including its original interest rate. The main feature is that the interest rate is quite low compared to current market rates. That's why assumable mortgages are incredibly helpful for buyers concerned about today's high mortgage rates. Instead of applying for a brand-new loan at a higher rate, the buyer steps into the seller's shoes and continues paying the existing loan under the same terms.
Which Mortgages Are Assumable?
Low-rate assumable loans are typically government-backed mortgages. These include
- FHA (Federal Housing Administration) loans
- VA (Veteran Affairs) loans
- USDA (United States Department of Agriculture) loans
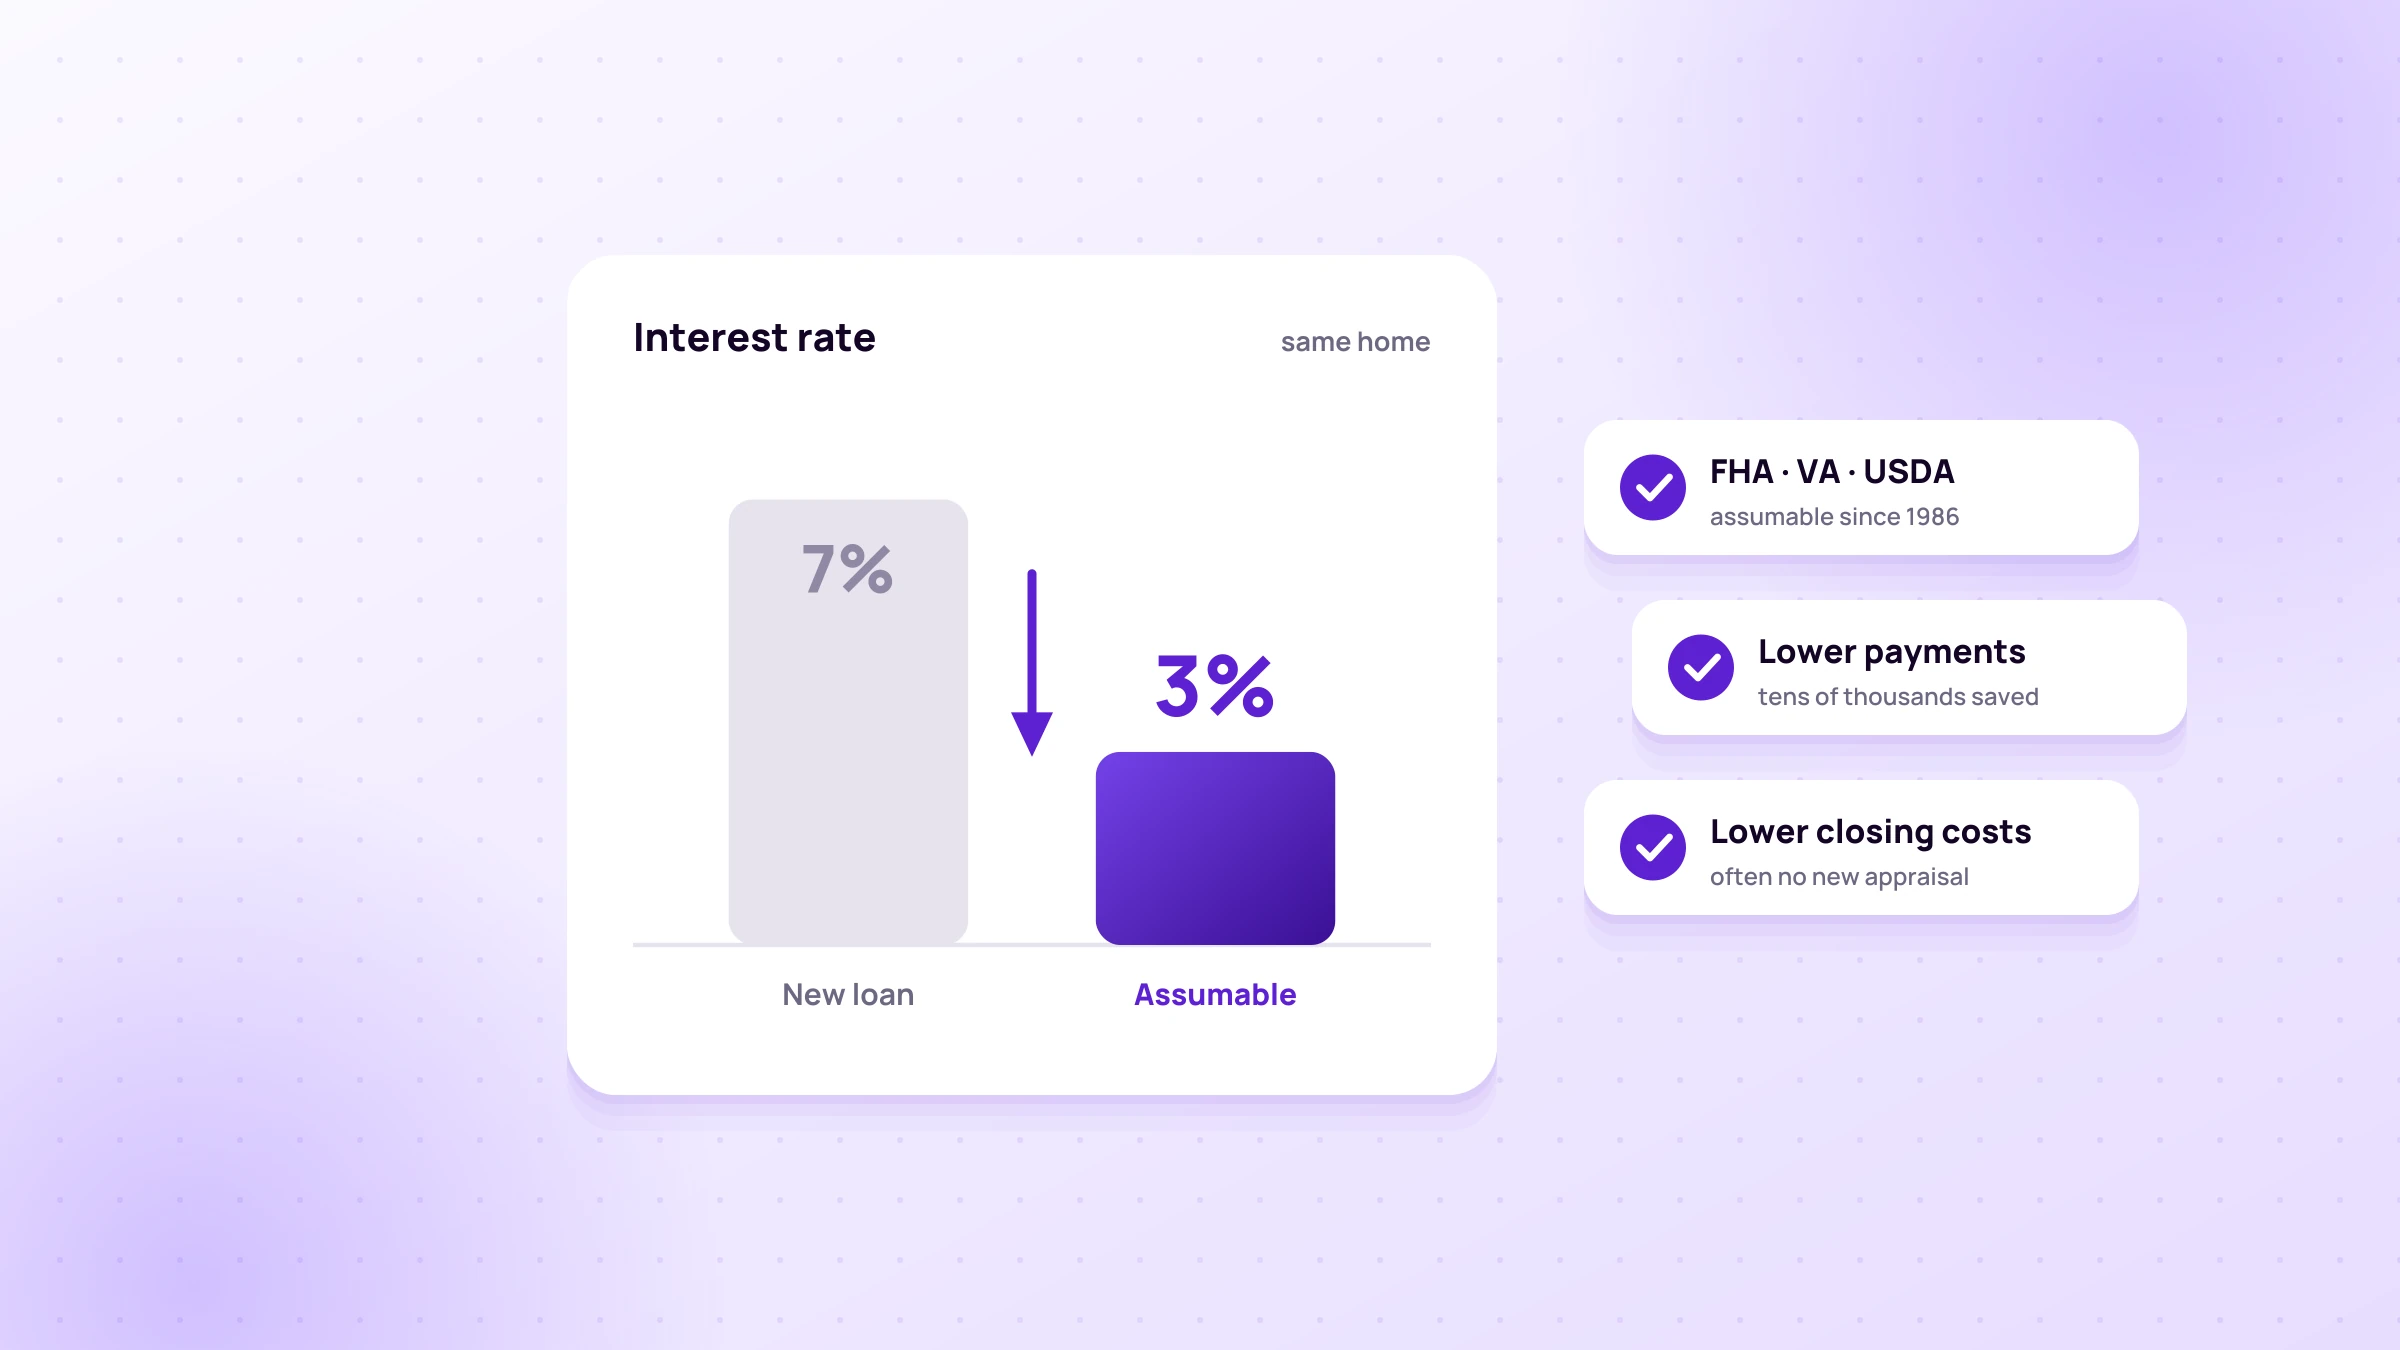
These types of loans have been assumable since 1986, offering favorable rates to buyers that were secured years earlier. Conventional loans are not usually assumable.
Benefits of Low-Rate Assumable Loans
Significant Savings for Buyers
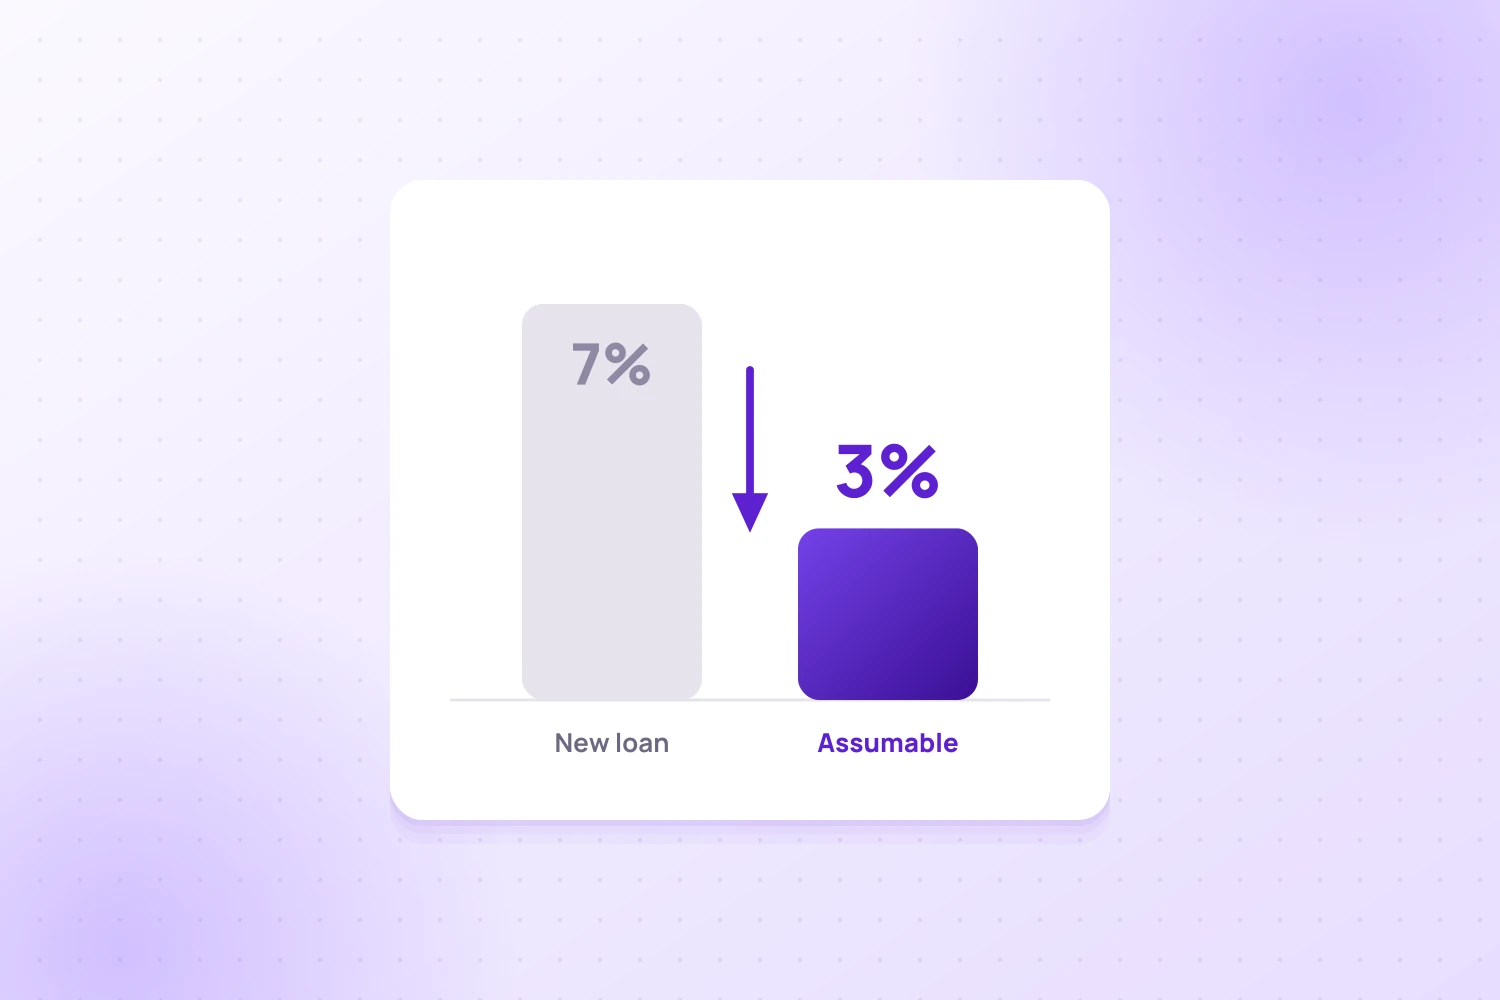
The main advantage is the potential for substantial savings. For example, if the seller's mortgage interest rate is 3% while current market rates are around 7%, assuming that loan can reduce monthly payments and lower the total interest paid by tens of thousands of dollars over the life of the loan. This makes homeownership much more affordable and accessible, especially when interest rates are rising.
Lower Closing Costs
Assumable loans often come with lower closing costs. The approval process is typically faster and more convenient compared to new mortgages. Buyers usually don't need to get a new appraisal, and lenders often have more flexible qualification standards, making the process less expensive and less time-consuming.
Advantages for Sellers
If you're a seller, offering a home with a low-rate assumable loan can make your property stand out. Here's how it benefits you
- Increase buyer interest by offering attractive financing options
- Command a higher sale price due to the value of the low-rate mortgage
- Transfer the original low interest rate and loan terms to the buyer
This arrangement is a win-win situation for both buyers and sellers. Buyers benefit from lower payments and reduced costs, while sellers enhance their home's marketability in today's elevated mortgage rate environment.
How to Find Assumable Loans Easily
If you want to benefit from an assumable mortgage, browse listings at Assumable.io. Our dedicated app showcases assumable mortgage listings nationwide, making it easy for you to find the right opportunity and take a meaningful step toward more affordable homeownership.